

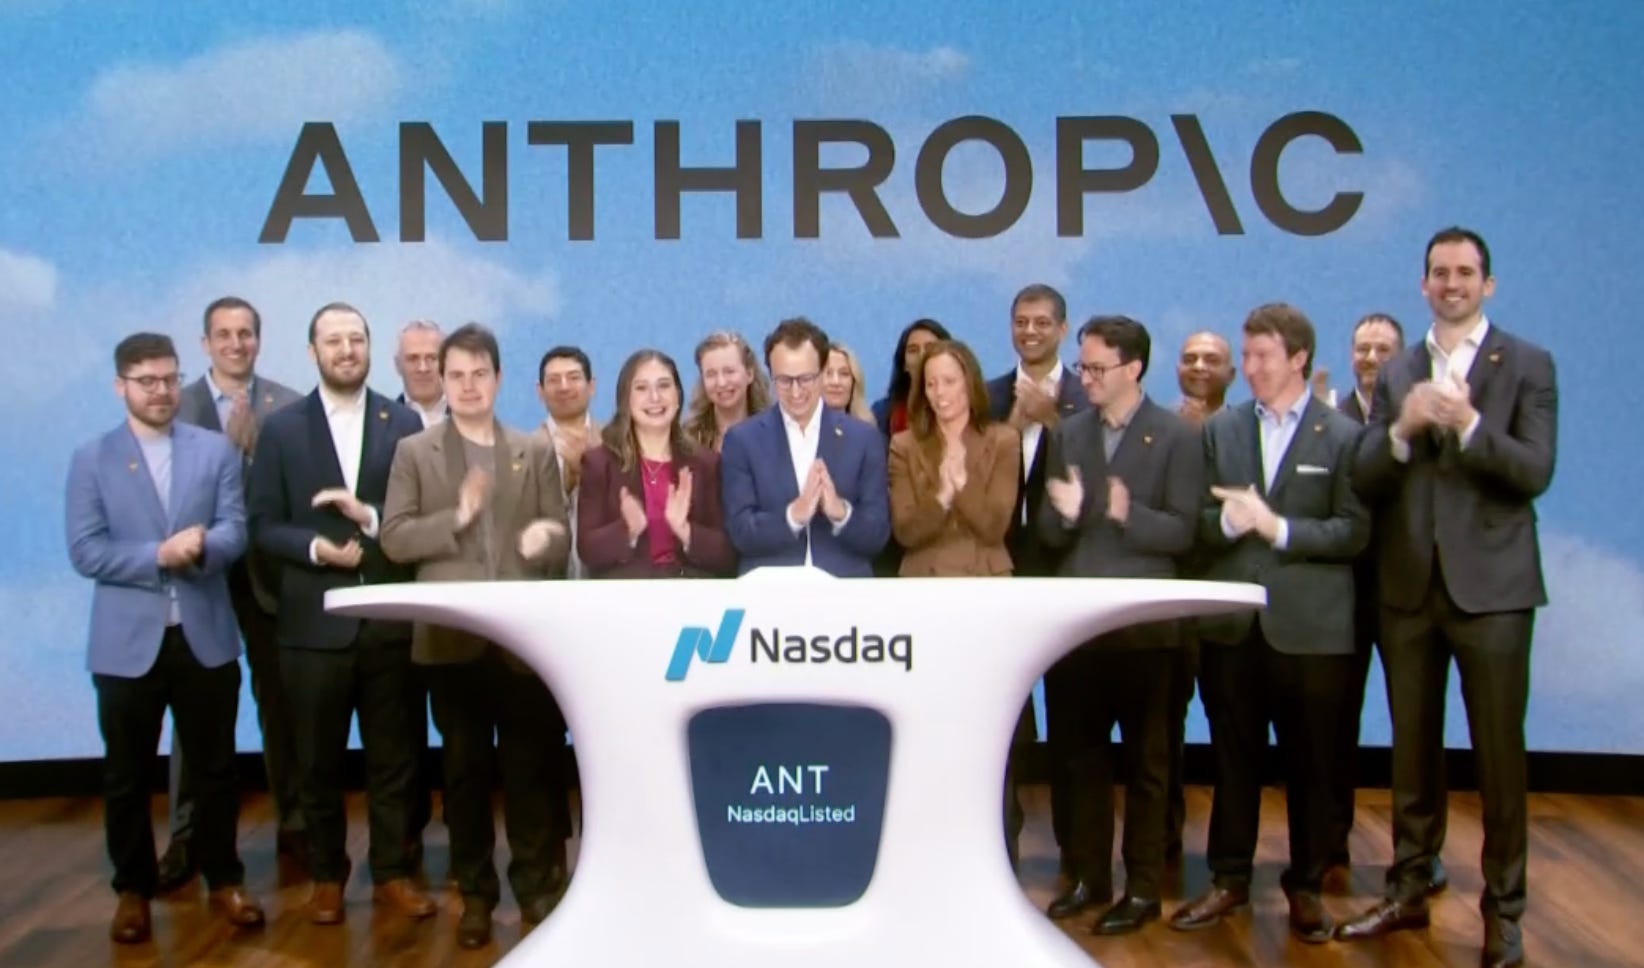
Anthropic raised a staggering $81 billion in its IPO Thursday, selling 980,000,000 shares at $83 a piece. The company’s shares are set to hit the public markets above $100 each, with a $2 trillion valuation in sight.
And so, after much debate about whether AI technology could become a real business, Anthropic just turned in the largest initial public offering in history.
The IPO is not the end of the story, though, as Anthropic will now be faced with plenty of challenges ahead. On Anthropic’s IPO day, we look at what got Anthropic here, and what’s next:
Speed
It’s hard to overstate just how fast Anthropic went from an idea to the world’s largest IPO. In the middle of Covid, the company’s co-founders sat outdoors in a San Francisco park, planning the company’s future in chairs they brought from home. Today, it’s become one of the world’s largest companies, a testament to the rapid pace of AI progress and how quickly the new technology is changing the world.
A correct bet on enterprise
Early in the generative AI era, Anthropic correctly bet on enterprise use cases. The idea was that A) Tackling harder enterprise problems would force it to build smarter models, and B) Getting these problems right could be very lucrative. Anthropic made this wager before there was consensus that AI models could become smart enough to handle these types of problems. It hit on the bet.
More than just an AI model company
In early 2025, Anthropic was mostly an AI model company. It sold its AI via an API, and its Claude chatbot was little used. Since then, the company has transformed its business. It is now an applications company with good AI models. Hits like Claude Code have moved Anthropic upstream. The company’s future rides on growing more Claude-Code-style applications for use in industries like manufacturing, life sciences, graphic design, healthcare, and general knowledge work.
Intense recent growth
Since making the applications pivot, Anthropic has grown furiously. It had 1,500 customers spending $100,000 or more in December 2025 and reached 11,900 such customers by September 2026. The company grew revenue by 147% between Q1 and Q2 in 2026 (from $4.7 billion to $11.6 billion) and another 47% in Q3 ($17 billion), demonstrating solid growth even after the tokenmaxxing craze fizzled.
A question of sustainability
Once the initial IPO excitement fades, Anthropic’s ability to sustain its momentum will come into question. The company’s customers are still working to determine AI’s ROI, and once-flowing budgets are starting to tighten. “Cost discipline” is AI’s new buzzword after runaway token spending dominated most of the first half of this year.
Challenges everywhere
Anthropic will also have to fend off challengers coming from all directions: Open weight models, cheap standard models from companies like Meta that competently get the job done, and model routers that switch customers off the frontier. And then there’s the public’s opposition to AI and the data centers that power it. This won’t be easy.
A sad trend for retail investors
SpaceX and Anthropic have both IPO’d at valuations well above $1 trillion. Companies waiting this long to IPO means most of the upside is captured in the private markets, leaving retail investors largely out of the wealth creation picture. It’s a shame, and will likely exacerbate the criticism around AI’s impact on income inequality.
Anthropic’s new dilemma
Anthropic has long claimed safety as a north star, but the public markets will test that commitment. Investors who prioritize quarterly revenue and profits may have less patience than VCs with multi-year commitment to the company. And the safety vs. revenue issue could get especially thorny as models get smarter and the balance becomes harder to maintain.
Enterprise AI Is Moving Beyond Pilots. Now What? — With Sergio Gago (sponsor)

Sergio Gago is the CTO of Cloudera. Sergio joins Big Technology to discuss how enterprise AI is moving from experimentation into production and what’s standing in the way. Tune in to hear why companies are bringing AI workloads back into their own data centers, how agents can send costs soaring, and why data governance is critical to making AI work. We also cover open-weight models, the economics of owning GPUs, data sovereignty, and what enterprise AI could look like in 2027. Hit play for a practical look at what it takes to turn AI’s promise into business results, in a conversation brought to you by Cloudera.
And don’t miss our conversation with Cloudera CRO Brian Rosso here.
Live this week on Big Technology Podcast:
Why The Anthropic IPO Will Succeed — With Aaron Levie

You can listen on Apple Podcasts, Spotify, or your podcast app of choice
Why The Anthropic IPO Will Fail — With Gary Marcus

You can listen on Apple Podcasts, Spotify, or your podcast app of choice
Thanks and see you next week!
On the sustainability point, look at how Anthropic actually gets paid. Of the $33.2 billion it booked in the first nine months of 2026, $26.3 billion, about 79%, came from consumption, tokens metered through Claude and the API. Subscriptions were only $6.9 billion.
That's great while usage is booming, but there's no contract to fall back on. When a CFO starts talking about "cost discipline," the token bill is one of the first things to get cut, and Anthropic sees it in the same quarter.
You can already see a bit of it. Revenue went from $4.7 billion in Q1 to $11.6 billion in Q2, so +$6.9 billion. Q3 added $5.4 billion. Still huge, but the quarterly add got smaller right when the tokenmaxxing craze faded, wich is what you'd expect from a business that charges by usage.
If I were buying ANT after the open, I'd watch the dollar add in Q4 more than the growth rate. If it keeps shrinking, a $1.4+ trillion valuation needs usage to speed up again, not just keep growing.